
Key takeaways
- Bumiputera SMEs in Malaysia have several financing options beyond conventional bank loans. These include peer-to-peer (P2P) financing, government-linked financing programmes and Shariah-compliant financing, depending on the business’s eligibility and funding requirements.
- microLEAP is a Bumiputera-owned P2P financing platform registered with the Securities Commission Malaysia (SC) as a Recognised Market Operator (RMO). The platform offers both Shariah-compliant and conventional financing options.
- P2P financing through microLEAP is available to eligible Malaysian businesses regardless of ownership. Financing starts from RM1,000, with different financing options available depending on the business’s requirements and eligibility.
- Eligibility generally requires a Malaysian-registered business with at least six months of operating history. All applications are subject to the platform’s credit assessment and approval process.
- Approval is not guaranteed. Financing eligibility, available financing amount and applicable terms are determined based on the business’s circumstances, credit assessment and the platform’s requirements.
- This article is for informational purposes only and does not constitute financial or legal advice.
Introduction
For Bumiputera business owners in Malaysia, securing financing does not necessarily mean relying solely on a traditional bank loan. Depending on the size and stage of the business, its financial track record and how quickly it needs funding, there are several financing routes to consider.
These include peer-to-peer (P2P) financing, government-linked financing programmes and Shariah-compliant financing options, each with different eligibility requirements, costs and financing structures.
microLEAP is a Bumiputera-owned Malaysian P2P financing platform registered with the Securities Commission Malaysia (SC) as a Recognised Market Operator (RMO).
This guide looks at the main financing options available to Bumiputera SMEs, the typical eligibility requirements, how P2P financing can serve as an alternative source of funding, and the costs businesses should consider before applying.
What financing options are available to Bumiputera SMEs in Malaysia?

Image: Financing options available to Bumiputera SMEs in Malaysia.
Bumiputera SMEs in Malaysia have several financing routes to consider, depending on the size and stage of the business, its financial track record and the purpose and urgency of its funding needs.
P2P financing. Peer-to-peer (P2P) financing allows businesses to raise funds from Investors through a regulated online platform. It can provide an alternative to traditional bank financing and is available to eligible businesses, subject to applicable Securities Commission Malaysia (SC) requirements and platform-specific eligibility criteria.
Bank financing. Banks offer various forms of business financing, including term financing and working capital facilities. Documentation, eligibility requirements and approval timelines vary by bank, product and the business’s circumstances.
Government-linked programmes. Agencies such as TERAJU, SME Corp Malaysia and MTDC offer programmes with their own eligibility criteria and availability. MyCIF is a government co-investment fund that supports eligible businesses through participating P2P and equity crowdfunding platforms, rather than a direct loan application route. Programme access and funding are subject to the relevant requirements.
Shariah-compliant financing. Businesses seeking an Islamic financing structure can consider Shariah-compliant options available through P2P financing platforms such as microLEAP. These options may be relevant to Bumiputera businesses that prefer or require financing structured in accordance with Shariah principles.
Ultimately, the appropriate financing route depends on the business’s financial position, funding requirements, eligibility and timeline. Businesses should compare the available options based on factors such as financing cost, tenor, repayment obligations and approval requirements before making a decision.
How does P2P financing work for Bumiputera SMEs?
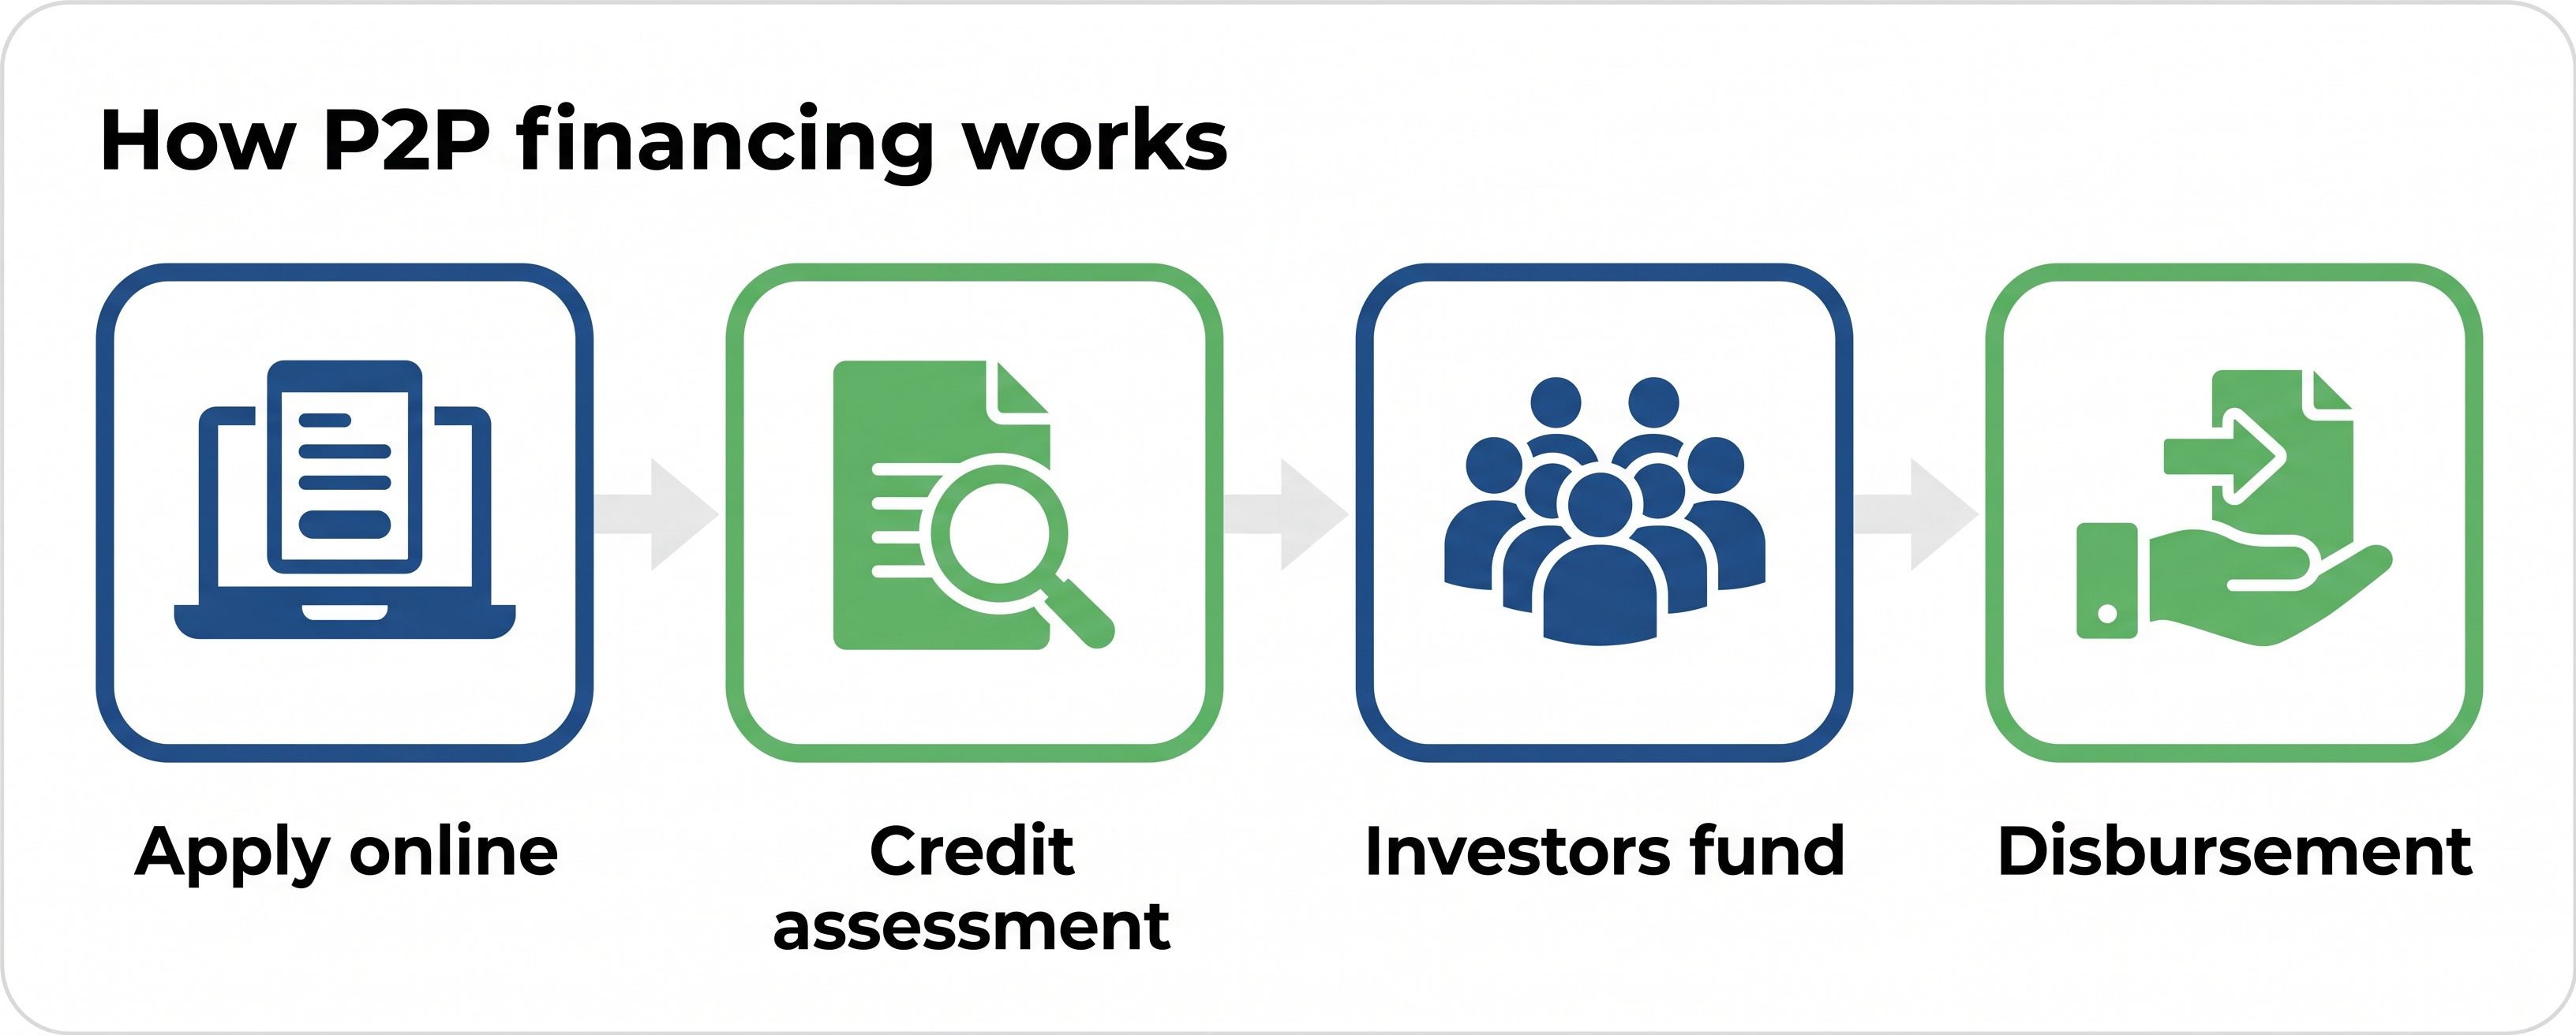
Image: A simplified illustration of the P2P financing process. Approval, successful funding and disbursement remain subject to the applicable assessment, funding threshold, documentation and other conditions.
P2P financing allows businesses to raise funds from individual Investors through a regulated online platform, providing an alternative to traditional bank financing.
The process typically begins with an online application and credit assessment. If the application is approved, the business’s financing request is listed on the platform for Investors to fund. Once the financing is fully funded, the funds are disbursed to the business in accordance with the approved financing structure and terms.
microLEAP offers several financing products for eligible Malaysian businesses:
- Micro Financing: RM1,000 to RM50,000, with a tenor of six to 36 months. Designed for smaller funding requirements, including operational expenses, inventory and equipment.
- Working Capital Financing: Up to RM500,000, with a tenor of six to 36 months. Intended to support day-to-day working capital requirements and business expansion.
- Invoice Financing: Up to RM1.5 million, with a tenor of up to 180 days and financing of up to 80% of the invoice value. Available to businesses with confirmed invoices from GLCs, government agencies or established corporates.
- Purchase Order (PO) Financing: Up to RM1.5 million, with a tenor of up to 180 days and financing of up to 80% of the PO value. Intended for businesses with confirmed purchase orders from credible buyers.
- SARANA: Up to RM1.5 million, with a tenor of three to 12 months. Available to eligible businesses registered on ePerolehan that have secured government contracts.
- Financial Support Letter (FSL): An official document issued by microLEAP confirming its commitment to finance a project if the business wins a tender. An FSL can strengthen a tender submission, but it does not represent a disbursement of funds.
Financing amounts start from RM1,000, subject to the applicable product requirements. Eligible Malaysian businesses can apply regardless of ownership, unless the business activity is restricted under applicable Securities Commission Malaysia (SC) regulations or platform requirements.
P2P financing is distinct from bank financing. microLEAP is registered with the SC as a Recognised Market Operator to facilitate financing between eligible businesses and Investors through its platform. It is not a bank, and funding depends on Investor participation and the applicable financing conditions.
Financing eligibility, amount, tenor and approval remain subject to credit assessment and the applicable product terms.
Is there Shariah-compliant financing available for Bumiputera businesses?

Image: Shariah-compliant financing for Bumiputera businesses on microLEAP.
Yes. microLEAP offers both Shariah-compliant and conventional financing through the same platform, allowing eligible businesses to select the financing structure that best matches their requirements and preferences.
The Shariah-compliant option uses a Commodity Murabahah (Tawarruq) structure, certified by Masryef Advisory. The cost of financing is the same for both Shariah-compliant and conventional financing, with microLEAP absorbing the applicable Shariah-related fees.
Eligible Bumiputera businesses can select their preferred financing structure when applying. The choice of structure does not change the underlying credit assessment or eligibility requirements. All applications remain subject to microLEAP’s credit assessment and approval process.
Choosing Shariah-compliant financing also does not eliminate credit risk. As with conventional P2P financing, financing remains subject to the business’s ability to meet its repayment obligations and the applicable financing terms.
Are there government-linked financing programmes for Bumiputera SMEs?
Yes. Bumiputera SMEs may be eligible for financing and support programmes offered through various government-linked agencies and initiatives. Eligibility, financing limits and application requirements vary between programmes.
microLEAP works with institutions including TERAJU, SME Corp, MTDC and MyCIF as institutional partners in supporting MSME financing.
One option available through microLEAP is SARANA, a programme under the Ministry of Finance and the Securities Commission Malaysia that facilitates access to P2P financing for eligible government vendors and GLC contractors. Eligible businesses can raise up to RM1.5 million under SARANA for qualifying government and GLC procurement, subject to the applicable requirements.
Businesses preparing to bid for contracts can also apply for a Financial Support Letter (FSL) from microLEAP. The letter can be used to demonstrate potential access to financing in support of a tender submission, but it does not constitute a financing approval or guarantee that funds will be disbursed.
Government-linked programmes are subject to their respective eligibility criteria and approval processes. Accessing these programmes through microLEAP does not guarantee approval or financing under any particular government initiative.
Who is eligible to apply for P2P financing on microLEAP?
microLEAP accepts applications from eligible Malaysian-registered businesses that have been operating for at least six months. The platform considers various business structures, including sole proprietorships, partnerships, limited liability partnerships (LLPs), Sdn Bhd companies and unlisted or listed public companies, subject to applicable Securities Commission Malaysia (SC) regulations and platform requirements.
Businesses will generally need to have:
- An active business bank account.
- At least six months of operating history.
- Basic financial records, including bank statements and management accounts, with audited financial statements where applicable.
- At least two personal guarantors and a corporate guarantee from the business for microLEAP financing.
- A credit profile that can be assessed and, where necessary, explained based on the circumstances of the business.
Meeting these requirements does not guarantee financing approval. Applications remain subject to credit assessment, document verification and microLEAP’s applicable requirements.
What should a business prepare before applying?
Having the relevant information and documents ready can help streamline the assessment process. The exact requirements may vary depending on the financing product, business profile and transaction.
Phase 1: Business and ownership verification
- Completed online application form.
- Business registration documents from SSM.
- Company profile.
- Identification documents for directors and ultimate beneficial owners, such as NRICs or passports for non-Malaysians.
Phase 2: Financial review
- Audited financial statements, where applicable.
- Latest management accounts.
- Bank statements covering the most recent six months.
Phase 3: Business and transaction validation
- Invoices, purchase orders or contracts, where applicable.
- Statement of the intended use of funds.
- Evidence of ongoing business operations.
- Other supporting documents that may be requested during the assessment.
Requirements can vary according to the financing structure, risk profile and nature of the transaction. Providing the requested documents allows the application to be assessed but does not guarantee approval or financing.
What does it cost to raise financing through microLEAP?
Businesses raising financing through microLEAP are subject to two main fees: an application fee and a platform fee.
- Application fee: RM50, non-refundable and payable upfront when the application is submitted.
- Platform fee: 2% to 8% of the approved financing amount, depending on the financing tenor. The platform fee is deducted from the financing proceeds before the funds are disbursed.
microLEAP does not charge monthly service fees or undisclosed fees. The applicable fees will be communicated to the applicant before the final financing terms are accepted.
Businesses should consider both the financing cost and the amount they will receive after applicable fees when assessing whether a financing option meets their funding requirements.
For an estimate of repayments and the total financing cost, businesses can use the Business Funding Calculator. Calculator results are estimates only and do not constitute an offer, financing approval or final financing terms.
Frequently asked questions about financing options for Bumiputera SMEs in Malaysia
Can a Bumiputera sole proprietorship apply for P2P financing?
Yes. microLEAP accepts eligible sole proprietorships and enterprises, provided they have been operating for at least six months, maintain an active business bank account and meet the platform’s credit assessment requirements.
All applications remain subject to the applicable eligibility criteria, document verification and credit assessment.
Can newly established Bumiputera businesses apply?
Generally, businesses must have been operating for at least six months before applying for financing through microLEAP. Businesses that have not yet reached this threshold may need to establish a longer operating history before applying.
Specific eligibility requirements may vary depending on the financing product.
How much can a Bumiputera SME raise through microLEAP?
The maximum financing amount depends on the product:
- Micro Financing: up to RM50,000.
- Working Capital Financing: up to RM500,000.
- Invoice Financing: up to RM1.5 million.
- Purchase Order Financing: up to RM1.5 million.
- SARANA: up to RM1.5 million for eligible government procurement.
Is P2P financing faster than a bank for Bumiputera SMEs?
The application process and approval timeline can vary between financing providers and products. For Micro Financing, microLEAP’s indicative credit decision period is three to five business days, subject to document completeness and the outcome of the credit assessment.
Other financing products may take longer depending on the complexity of the application and the supporting documentation required. An indicative timeline is not a guarantee of approval or disbursement.
Can a Bumiputera SME get Shariah-compliant P2P financing?
Yes. microLEAP offers Shariah-compliant financing using a Commodity Murabahah (Tawarruq) structure, overseen by Masryef Advisory.
The cost of financing is the same as for conventional financing, and eligible businesses can select their preferred structure when applying. The choice of Shariah-compliant financing does not change the eligibility requirements or credit assessment process.
Does microLEAP support Bumiputera businesses applying for government tenders?
Yes. microLEAP participates as an approved P2P financing platform under SARANA, supporting eligible registered vendors undertaking government and GLC procurement.
Businesses can also apply for a Financial Support Letter (FSL) from microLEAP to support a tender submission before financing is confirmed. An FSL does not constitute financing approval or guarantee that funds will subsequently be disbursed.
Eligibility for SARANA and other government-linked programmes is subject to the requirements of the respective programme. Access through microLEAP does not guarantee approval.
Conclusion
Bumiputera SMEs in Malaysia have several financing routes beyond traditional bank financing, including P2P financing, government-linked programmes and Shariah-compliant options. Each comes with different eligibility criteria, financing costs, tenors and repayment obligations.
The appropriate route depends on the business’s stage of development, funding requirements, financial position and the amount of financing needed. For eligible businesses seeking a digital financing option, P2P financing through microLEAP is one alternative to consider.
As with any financing application, eligibility and approval are subject to credit assessment, supporting documentation and the applicable platform and product requirements.
This article is for informational purposes only and does not constitute financial or legal advice.
For a more detailed overview of the application process, eligibility and financing options, see P2P Financing for Small Businesses in Malaysia.
Businesses interested in exploring their financing options can visit microLEAP's Raise Funds page to begin an application.
Regulatory and advertising disclosures
This advertisement has not been reviewed by the Securities Commission Malaysia.
microLEAP PLT is registered with the Securities Commission Malaysia as a Recognised Market Operator to operate a P2P financing platform. Registration with the SC does not constitute a recommendation or endorsement by the SC of microLEAP, any financing product or any application.
Financing is subject to eligibility, identity and business verification, credit and compliance assessment, approval, achievement of the applicable funding threshold and completion of the required documentation. Approval, financing amount, rate, tenor, successful funding and disbursement are not guaranteed.
Applicable financing or profit rates, fees, taxes, charges and other deductions will be disclosed in the relevant offer and final financing documents.
Any calculator results are estimates for illustrative purposes only and do not constitute an offer, financing approval or final financing terms.
Before applying or accepting financing, applicants should review the microLEAP Issuer Agreement and Terms and Conditions, together with the applicable product, offer and financing documents, for the full terms and applicable charges.