Key takeaways
- Registration is not an endorsement. microLEAP PLT is registered with the Securities Commission Malaysia (SC) as a Recognised Market Operator (RMO). This registration should not be interpreted as an endorsement or recommendation by the SC of microLEAP, its financing products or any individual financing application.
- Verify registration independently. Before submitting an application or supporting documents, businesses should verify the platform’s registration status against the SC’s official register of RMOs.
- Regulatory requirements govern platform operations. As an RMO, microLEAP is subject to applicable regulatory requirements, including Issuer credit assessments, the use of segregated trust accounts for funds and disclosure of relevant rates, fees and terms. Businesses should review the applicable disclosures and financing terms before accepting an offer.
- Financing is subject to assessment and approval. All applications are subject to eligibility requirements, credit assessment and approval. Approval, financing amounts, rates, tenors, successful funding and disbursement are not guaranteed.
- Review the agreement before committing. Businesses should review the Issuer Agreement in full before accepting financing, paying particular attention to the parties’ respective obligations, repayment terms, applicable fees and other contractual conditions.
Introduction
Businesses exploring peer-to-peer (P2P) financing may want to establish whether a platform is legitimately registered and subject to regulatory oversight before submitting an application. Registration matters, but it should not be mistaken for an endorsement. It signifies that the platform operates within an applicable regulatory framework and is subject to specific requirements that businesses can verify independently.
microLEAP PLT is registered with the Securities Commission Malaysia (SC) as a Recognised Market Operator (RMO) to operate a P2P financing platform. On microLEAP, a business seeking financing is referred to as an Issuer.
This article examines what SC regulation means in practice, the disclosure and process requirements relevant to businesses seeking financing, how to verify a platform’s registration on the SC’s official register, and the key contractual terms to review before applying.
For a broader overview of P2P financing products and the application process, see P2P Financing for Small Businesses in Malaysia.
What does SC RMO registration mean for P2P platforms in Malaysia?
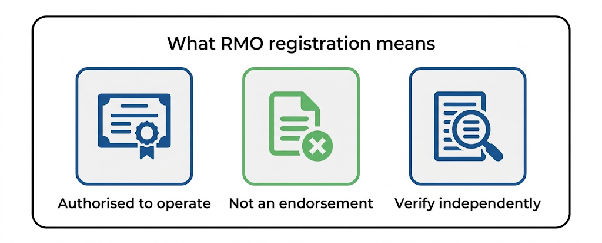
Image: What RMO registration means for a P2P platform in Malaysia.
An operator registered with the SC to operate a P2P financing platform may conduct such activities subject to its registration conditions and applicable regulatory requirements.
For businesses considering P2P financing, this registration provides a starting point for verifying a platform’s regulatory status.
- Registration is a regulatory requirement. Only operators registered with the SC as RMOs are permitted to operate P2P financing platforms in Malaysia under the applicable regulatory framework.
- Registration is not an endorsement. The SC’s registration does not constitute a recommendation or endorsement of the platform, its financing products or any individual financing application. Businesses should assess the platform and its financing terms independently.
- Registration can be independently verified through the SC’s official Digital Initiatives page. Under the Peer-to-Peer Financing list, locate microLEAP PLT and use the website link provided by the SC to access the platform. Before submitting applications, sharing documents or paying fees, verify that the legal entity and website address match the information listed by the SC.
- microLEAP PLT is included in the SC’s list of registered P2P platform operators. Its business registration numbers, as stated in its platform terms, are 201804001722 and LLP0016104-LGN.
RMO registration is an important first step in verifying a P2P financing platform. However, it does not guarantee financing approval or eliminate the commercial risks associated with borrowing. Businesses should review the applicable financing terms, fees and contractual obligations before proceeding.
What does SC regulation require of a P2P platform in Malaysia?
As a Recognised Market Operator (RMO), microLEAP is subject to the Securities Commission Malaysia’s (SC) regulatory requirements for P2P financing. These include assessing Issuers’ creditworthiness, ensuring funds are held in segregated trust accounts, and providing relevant disclosures on financing rates, fees and terms before an Issuer accepts a financing offer.
Key requirements and practices include:
- Credit assessment before listing. microLEAP conducts a credit assessment of each Issuer before listing a financing request. This includes assigning a credit risk score based on the business application and conducting checks with external credit reference agencies.
- Segregated trust accounts. Funds raised through the platform are held in segregated trust accounts administered by an independent trustee, Universal Trustee (Maybank Trustees Berhad), rather than held directly by microLEAP. This separation helps distinguish funds held for platform transactions from the platform’s own operating funds.
- Disclosure of financing terms. Applicable rates, fees, charges and deductions are disclosed before the Issuer accepts the final financing terms, enabling the business to review its financing obligations before committing.
- Contractual obligations. The financing arrangement between the Issuer and Investors is governed by the relevant financing agreement and the applicable regulatory framework for P2P financing.
These are not merely optional platform features; they form part of the regulatory and operational framework governing P2P financing, which includes SC requirements such as credit assessment and designated trust accounts. Platform-specific eligibility criteria, fees and contractual processes are separate considerations, and compliance with applicable requirements does not guarantee approval, funding or disbursement. However, regulatory compliance does not guarantee that a financing application will be approved, that an Issuer will secure its target funding, or that repayment obligations will be met.
How can an MSME verify a P2P platform’s SC registration in Malaysia?
Before applying for P2P financing, micro, small and medium enterprises (MSMEs) should independently verify that the platform is registered with the Securities Commission Malaysia (SC) as a Recognised Market Operator (RMO). This helps establish whether the platform is authorised to operate within Malaysia’s regulatory framework for P2P financing.
Businesses can do so by checking the SC’s official register of Recognised Market Operators before submitting applications, providing supporting documents or making payments.
microLEAP PLT (Registration No. 201804001722; LLP No. LLP0016104-LGN) is listed on the SC’s register as a RMO.
Businesses should exercise caution when dealing with platforms whose registration status cannot be verified on the SC register. They should also confirm that any communications and payment instructions genuinely originate from the registered operator.
Verifying registration is an important first step in due diligence. However, it does not constitute an endorsement by the SC or guarantee financing approval, the performance of a financing arrangement or the absence of financial risk.
What should an MSME know before applying for P2P financing on microLEAP?
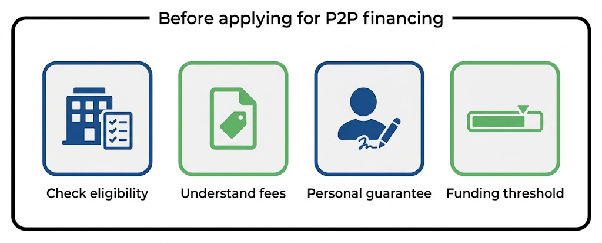
Image: What an MSME should check before applying for P2P financing on microLEAP.
Before applying for P2P financing through microLEAP, a business should understand the eligibility criteria, applicable fees, potential personal guarantee obligations and contractual terms set out in the Issuer Agreement. These details should be reviewed carefully before the business commits to a financing arrangement.
Key considerations include:
- Eligibility requirements: The business must be registered in Malaysia, have been operating for at least six months, maintain an active business bank account and have basic financial records available for assessment. All applications remain subject to eligibility checks, credit assessment and approval.
- Application and platform fees: A non-refundable application fee of RM50 applies, alongside a one-time platform (Issuer) fee of 2% to 8% of the financing amount, depending on the tenor, which is deducted before disbursement. Businesses should check the current fee schedule and final offer for the applicable fees, any waivers, taxes and other charges.
- Personal guarantees: Directors and/or shareholders may be required to provide a personal guarantee and indemnity as a condition of financing approval. Businesses should understand the potential personal liability arising from these commitments before proceeding.
- Funding threshold: A financing campaign must reach at least 80% of its target amount within the specified funding period for disbursement to proceed, subject to the applicable terms and conditions.
- Concurrent applications: Businesses cannot list on multiple P2P financing platforms concurrently for the same financing purpose.
The applicable financing rates, fees, charges and conditions should be disclosed before the business accepts a financing offer. Businesses should review the Issuer Agreement in full, including repayment obligations, fees, guarantees and other contractual commitments, before accepting the final terms.
Meeting the eligibility requirements does not guarantee approval, successful funding or disbursement.
Frequently asked questions about SC-regulated P2P financing for MSMEs
What is a Recognised Market Operator in Malaysian P2P financing?
A Recognised Market Operator (RMO) is an operator registered with the Securities Commission Malaysia (SC) to operate a P2P financing platform, subject to the applicable regulatory requirements. Businesses can verify a platform’s registration status through the SC’s official register before submitting an application.
Does SC registration mean a P2P platform is endorsed or recommended?
No. Registration confirms that the platform is authorised to operate within the applicable regulatory framework. It does not constitute an endorsement or recommendation by the SC of the platform, its financing products or any individual financing application.
Can any Malaysian business apply for P2P financing on microLEAP?
Not all businesses are eligible. Applicants must be registered in Malaysia, have at least six months of operating history, maintain an active business bank account and meet the applicable eligibility and credit assessment requirements. All applications are subject to assessment and approval, and meeting the basic criteria does not guarantee financing.
What happens to outstanding financing and repayments if microLEAP ceases operations?
If microLEAP ceases operations or becomes insolvent, the published Issuer Agreement provides for servicing obligations to be transferred to an appointed independent third-party service provider under the applicable backup arrangements. The Issuer’s repayment obligations under the relevant financing documents remain in force, and businesses should follow verified instructions issued by the authorised servicing party.
Is P2P financing in Malaysia available as a Shariah-compliant option?
Yes. microLEAP offers both Shariah-compliant and conventional financing structures. Its Shariah-compliant financing uses a Commodity Murabahah arrangement via Tawarruq, structured in accordance with the applicable Shariah requirements.
How does P2P financing differ from a bank loan for Malaysian MSMEs?
P2P financing is facilitated through an online platform, with funding provided by Investors rather than directly by a bank. The application process is digital, and assessment criteria may differ from those applied by traditional banks. An unsuccessful bank financing application does not automatically make a business ineligible for P2P financing. However, all applications remain subject to the platform’s eligibility requirements, credit assessment and approval.
For a detailed comparison of the two financing options, see P2P Financing vs Bank Loans for Malaysian MSMEs: A Funding Comparison.
Conclusion
Registration with the Securities Commission Malaysia (SC) as a Recognised Market Operator (RMO) confirms that microLEAP is authorised to operate a P2P financing platform and is subject to the applicable regulatory requirements. However, registration does not constitute an endorsement of the platform or guarantee the approval or outcome of any financing application.
Businesses can independently verify microLEAP’s registration on the SC’s official register before applying. They should also assess the applicable eligibility criteria, fees and any personal guarantee obligations before proceeding.
Before accepting a financing offer, businesses should carefully review the Issuer Agreement governing their relationship with microLEAP, as well as the separate Funding Contract and applicable financing documents setting out their obligations to Investors. Particular attention should be paid to the repayment schedule, fees, guarantees and other contractual commitments.
All financing applications remain subject to eligibility checks, credit assessment and approval. Financing amounts, rates, tenors, successful funding and disbursement are not guaranteed. For the full terms and conditions, refer to microLEAP’s applicable platform documentation.
Regulatory and advertising disclosures
This advertisement has not been reviewed by the Securities Commission Malaysia.
microLEAP PLT is registered with the Securities Commission Malaysia as a Recognised Market Operator to operate a P2P financing platform. Registration with the SC does not constitute a recommendation or endorsement by the SC of microLEAP, any financing product or any application.
Financing is subject to eligibility, identity and business verification, credit and compliance assessment, approval, achievement of the applicable funding threshold and completion of the required documentation. Approval, financing amount, rate, tenor, successful funding and disbursement are not guaranteed.
Applicable financing/profit rates, fees, taxes, charges and deductions will be disclosed in the relevant offer and final documents. Calculator results are estimates only and do not constitute an offer, approval or final financing terms.